Statement
The Frechet distribution is the positive-shape extreme-value law for normalized maxima with heavy right tails. In the standard one-parameter form with shape , its CDF is
For , the density is
It is the member of the generalized extreme-value distribution. With , location , and scale ,
The phrase Frechet-type refers to distributions whose normalized maxima converge to this law. In the usual right-tail setting, this is the regularly varying maximum-domain-of-attraction case: a Pareto-type survival tail with exponent has extreme-value index . Here is the parent CDF, its survival function, its iid draws, and the lower cutoff in the exact Pareto example. and denote the Frechet CDF and density.
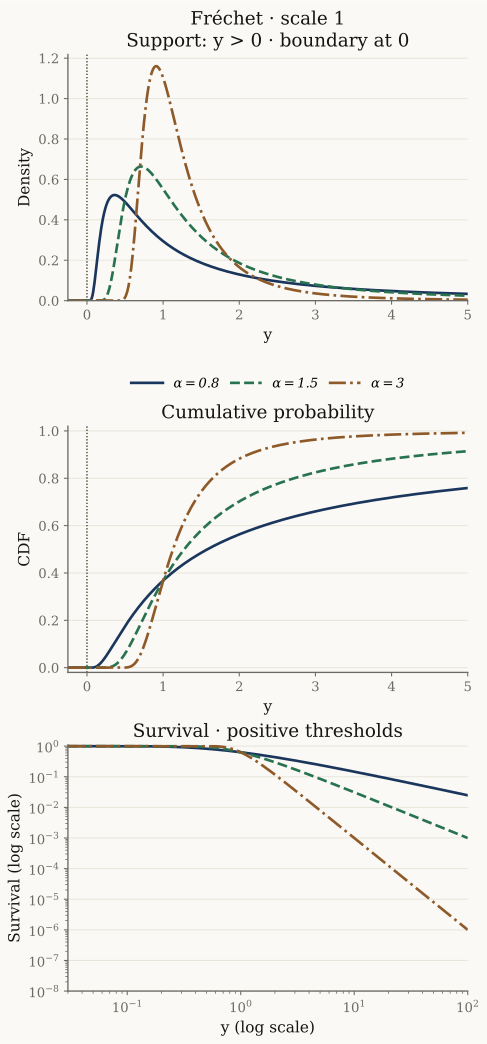
Figure 1:Unit-scale Fréchet laws with , using the same exponent colors as the Pareto card. The boundary is zero. Survival approaches a power tail at large positive thresholds; it is not an exact power over the whole support. The last panel’s lower visible probability is 10-8.
Maxima interpretation
Frechet-type behavior is a statement about extremes, not necessarily about the full parent distribution. If are iid and the right tail is regularly varying with exponent , then an appropriate positive normalization puts the maximum
on the Frechet scale. The full regular-variation domain-of-attraction theorem is cited in the references; the exact Pareto calculation below shows the core mechanism.
For Pareto Type I with lower cutoff and exponent , take . Then for fixed and all large enough ,
The same shape parameter is therefore seen in two coordinates:
Tail behavior
Although the Frechet law is a limit law for maxima, it is itself heavy-tailed. Its survival function satisfies
Thus the Frechet survival tail is regularly varying with index . This is why the GEV regime is also the Pareto-type regime: the block-maximum limit and the parent survival tail share the same reciprocal coordinate .
Finite-block calculation
For any , the exact Pareto probability at is . The limit is , independently of because the normalization already includes .
| Block size | Exact | Frechet limit |
|---|---|---|
| 10 | 0.348678 | 0.367879 |
| 100 | 0.366032 | 0.367879 |
| 600 | 0.367573 | 0.367879 |
For fixed , set . Expanding the logarithm gives
This explains the finite-block correction for an exact Pareto parent at a fixed . It is not a uniform error bound over all thresholds or a rate for arbitrary regularly varying parents. No simulated or fitted CDF is used here.
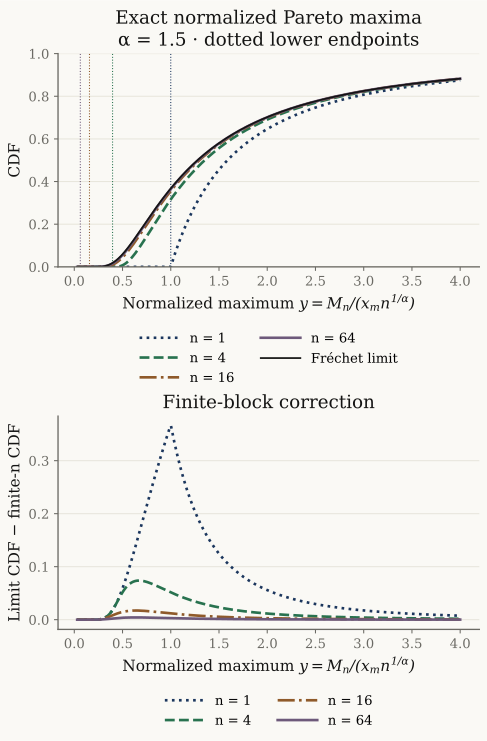
Figure 2:Exact population CDFs for iid Pareto parents with and normalization ; no maxima are simulated or fitted. Dotted lines mark the finite-block lower boundaries . The second panel plots the limit CDF minus each finite-block CDF, making small corrections visible without displacing overlapping curves.
Use frechet and the existing
pareto_normalized_maximum_cdf.
from xmath.incerto.distributions import frechet
from xmath.incerto.glossary import pareto_normalized_maximum_cdf

for n in (1, 4, 16, 64):
    finite = pareto_normalized_maximum_cdf([1], alpha=1.5, n=n)[0]
    print(f"n={n:d}: cdf(1)={finite:.4g}, limit={frechet(1.5).cdf(1):.4g}")
Output
n=1: cdf(1)=0, limit=0.3679
n=4: cdf(1)=0.3164, limit=0.3679
n=16: cdf(1)=0.3561, limit=0.3679
n=64: cdf(1)=0.365, limit=0.3679
Regenerate both figures with uv run python demos/incerto/distribution_cards.py.
Caveats
Frechet-type is a domain-of-attraction label. It does not say the original observations themselves follow a Frechet distribution.
The conclusion is asymptotic. Finite samples can look Frechet-like over one range and deviate elsewhere because of body contamination, dependence, truncation, censoring, or second-order tail behavior.
GEV block-maxima fitting uses a location-scale family. The unit Frechet law above is a convenient standard representative of the positive-shape class.
References
Embrechts, Klueppelberg, and Mikosch, Modelling Extremal Events 1997.
Resnick, Heavy-Tail Phenomena 2007.
Coles, An Introduction to Statistical Modeling of Extreme Values 2001.
Backlinks
Depends on: Generalized Extreme-Value Distribution, Pareto Distribution, and Regular Variation.
Used by: Extreme Value Index Estimation and the positive-shape regime of Generalized Extreme-Value Distribution.
- Embrechts, P., Klüppelberg, C., & Mikosch, T. (1997). Modelling Extremal Events. Springer. 10.1007/978-3-642-33483-2
- Resnick, S. I. (2007). Heavy-Tail Phenomena: Probabilistic and Statistical Modeling. Springer. 10.1007/978-0-387-45024-7
- Coles, S. (2001). An Introduction to Statistical Modeling of Extreme Values. Springer. 10.1007/978-1-4471-3675-0