Overview¶
An exact Pareto tail has the same probability ratio whenever we multiply a threshold by a fixed amount. Regular variation asks for this behavior only in the limit as the threshold grows. It allows slow corrections to a power law while retaining a limiting tail exponent.
Read the Pareto survival example first for a concrete example. This page uses limits and positive measurable functions; the proof below establishes the power-times-slowly-varying characterization directly from the definition.
Definition and characterization¶
A positive measurable function is regularly varying at infinity with index , written , if, for every fixed ,
The case is called slow variation: a positive measurable function is slowly varying when for every fixed . Equivalently, regularly varying functions can be written as
with slowly varying. A survival function has a regularly varying right tail with exponent , written , when
Here , is the slowly varying factor, is the positive tail exponent, and is a fixed multiplier.
What the ratio means¶
Regular variation is the mathematical version of Pareto-style scale invariance. At high thresholds, multiplying the threshold by has an asymptotically stable effect on exceedance probabilities. The slowly varying factor allows departures from an exact Pareto law while preserving the same tail exponent.
The ratio statement is stronger than saying that large observations are more frequent than under a Gaussian baseline. It says that the relative penalty for raising a large threshold settles to a power .
Examples and non-examples¶
Constant functions are slowly varying. If , then for every and .
Logarithmic corrections are slowly varying. For fixed , on satisfies .
A nonzero power is not slowly varying. If , then , which equals 1 for all only when .
Lognormal right tails are heavy-tailed and subexponential, but not regularly varying: their fixed-multiplier survival ratios do not settle to for any finite .
Exponential tails are neither regularly varying nor subexponential. For a multiplier , their survival ratios decay exponentially in .
Proof of the characterization¶
We prove the algebraic characterization used throughout these notes: a regularly varying function is a power times a slowly varying function. The proof is only an unwinding of the ratio definition. The Karamata note develops the related integral asymptotics and their moment consequences.
If with slowly varying, then for fixed ,
Conversely, if , define . Then
so is slowly varying and .
For survival tails, set in the same equivalence: , with slowly varying. No separate survival-tail argument is needed.
For the Pareto distribution with lower cutoff ,
so is constant and therefore slowly varying.
What the representation theorem adds¶
The elementary equivalence above defines ; it does not prove Karamata’s representation theorem. For positive measurable slowly varying , that theorem gives, eventually,
with measurable and locally integrable . We cite the existence of this representation: Bingham et al. (1987), Theorem 1.3.1, p. 12. This is a different result from the integral theorem.
Its sufficiency follows directly. For fixed , the logarithm of is . The integral’s absolute value is at most times the supremum of between and , which tends to zero. Also : split the integral at a fixed point beyond which , divide by , and then let . Hence a regularly varying survival satisfies . This is a ratio of logarithms; convergence of a derivative of a log-log plot needs extra smoothness.
Positive powers of a tail variable¶
We prove the transformation rule used in SCoFT v4 §5.2.3, p. 100 Taleb, 2025, without differentiating a density. Let have eventually and let . Then
For fixed , the ratio of the last slowly varying factors has arguments and , so it tends to one. Thus has survival exponent . Units may be fixed first by applying this argument to . Negative powers concern the behavior near zero and are outside this right-tail rule. The exact Pareto payoff case is already derived in asymmetric payoffs.
Ratio diagnostics¶
The fixed-multiplier ratio can be compared algebraically for an exact Pareto tail and a power law with a slowly varying logarithmic correction.
For an exact Pareto tail and a logarithmically corrected tail, respectively,
For and , the correction multiplier is 2 at , at , and at . The second expression is used only sufficiently far into the tail, where it is decreasing and at most one before taking the ratio; a full distribution also needs a body below that range.
The exact Pareto ratio is constant at ; the log-corrected ratio approaches the same target slowly. A finite diagnostic curve can suggest regular variation, but the definition is about the asymptotic limit.
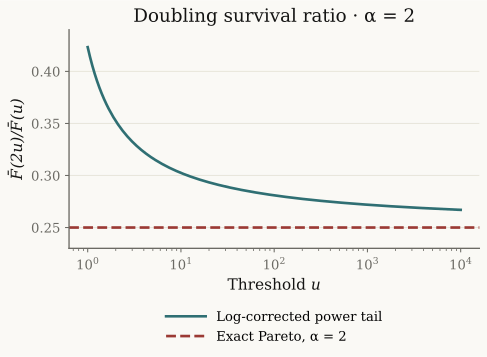
Figure 1:This reused chapter-2 figure uses for , extended by one below 1. It has exponent 2 and slowly varying factor , differing from the preceding exponent-1.5 example with factor . Its doubling ratio is , which approaches . All values are population evaluations; the threshold axis is logarithmic.
Use regular_variation_ratio
to evaluate the law used in the figure:
import numpy as np
from xmath.incerto.tail_diagnostics import regular_variation_ratio

survival = lambda u: u**-2 * (1 + np.log(u))
result = regular_variation_ratio(survival, [1, 10, 100, 10000])
for u, ratio in zip(result["threshold"], result["ratio"]):
    print(f"u={u:.4g}: ratio={ratio:.4g}, limit=0.25")
Output
u=1: ratio=0.4233, limit=0.25
u=10: ratio=0.3025, limit=0.25
u=100: ratio=0.2809, limit=0.25
u=1e+04: ratio=0.267, limit=0.25
The existing producer is uv run python demos/incerto/glossary_worked_cases.py.
The chapter 5 demo compares multiplier ratios for Student and shifted double-Pareto tails. Their finite threshold differences are explained by the matching calculation.
Caveats¶
Regular variation is an asymptotic property. It does not say that every moderate observation follows a power law.
Estimating from finite samples is threshold-sensitive; the Hill estimator and log-log plots are diagnostics, not certificates.
A nonnegative law with a regularly varying right tail and is subexponential (Foss, Korshunov, and Zachary, 2nd ed., §3.5, Theorem 3.29 and following paragraph, p. 57); see Subexponentiality for the one-big-jump principle.
Moment implications require assumptions on the full tail and should point to Karamata’s theorem or to a Pareto-specific proof.
References¶
Foss, Korshunov, and Zachary, An Introduction to Heavy-Tailed and Subexponential Distributions, 2013, 2nd ed., §3.5, Theorem 3.29, p. 57: cited subexponential classification.
Bingham et al. (1987), Regular Variation, Theorem 1.3.1, p. 12: the cited representation theorem; the elementary power-times- characterization is proved on this page.
Taleb (2025), §5.1.1, pp. 95–97, and §5.2.3, p. 100: scaling and transformation context.
Embrechts, Klueppelberg, and Mikosch, Modelling Extremal Events 1997.
Resnick, Heavy-Tail Phenomena 2007.
Backlinks¶
Used by: Pareto Distribution, Double Pareto Distribution, Subexponentiality, Tail Class Catalog, Pareto Moment Existence, Generalized Central Limit Theorem, and Hill Estimator.
- Bingham, N. H., Goldie, C. M., & Teugels, J. L. (1987). Regular Variation. Cambridge University Press. 10.1017/CBO9780511721434
- Taleb, N. N. (2025). Statistical Consequences of Fat Tails (3rd ed.). https://arxiv.org/abs/2001.10488v4
- Foss, S., Korshunov, D., & Zachary, S. (2013). An Introduction to Heavy-Tailed and Subexponential Distributions (2nd ed.). Springer. 10.1007/978-1-4614-7101-1
- Embrechts, P., Klüppelberg, C., & Mikosch, T. (1997). Modelling Extremal Events. Springer. 10.1007/978-3-642-33483-2
- Resnick, S. I. (2007). Heavy-Tail Phenomena: Probabilistic and Statistical Modeling. Springer. 10.1007/978-0-387-45024-7