Statement¶
Let have a Pareto Type I distribution with lower cutoff and tail exponent :
For any moment order ,
When ,
At , the truncated moment diverges logarithmically. For , it diverges as a power of the upper cutoff. In particular, the Pareto mean exists only for , and the variance exists only for .
Here denotes survival probability and denotes expectation; is a positive moment order.
Proof by direct integration¶
We prove the Pareto Type I moment boundary and the moment formula by direct integration. The same calculation also explains the logarithmic boundary and power-divergent regimes in the truncated-moment section. The broader regularly varying moment test is handled by Karamata’s Theorem.
For , the Pareto density is
For ,
The integral converges exactly when , equivalently . Evaluating the convergent case gives
Adding to both sides proves the algebraic equivalence .
This exact Pareto calculation is the simplest instance of the Karamata moment test for regularly varying tails.
Truncated-moment behavior¶
For a finite upper cutoff , define
Direct integration gives
Thus the same theorem has three operational regimes: convergence to a finite moment, logarithmic boundary growth, and power growth.
For and , the three regimes reduce to:
| Moment order | Truncated moment , | Limit as |
|---|---|---|
| 1 | 3 | |
| 1.5 | Infinite, logarithmic growth | |
| 2 | Infinite, power growth |
For , the truncated moment levels off. At , it keeps growing, but only logarithmically. For , the upper tail contributes a visible power-law rise.
Products and moment integrals¶
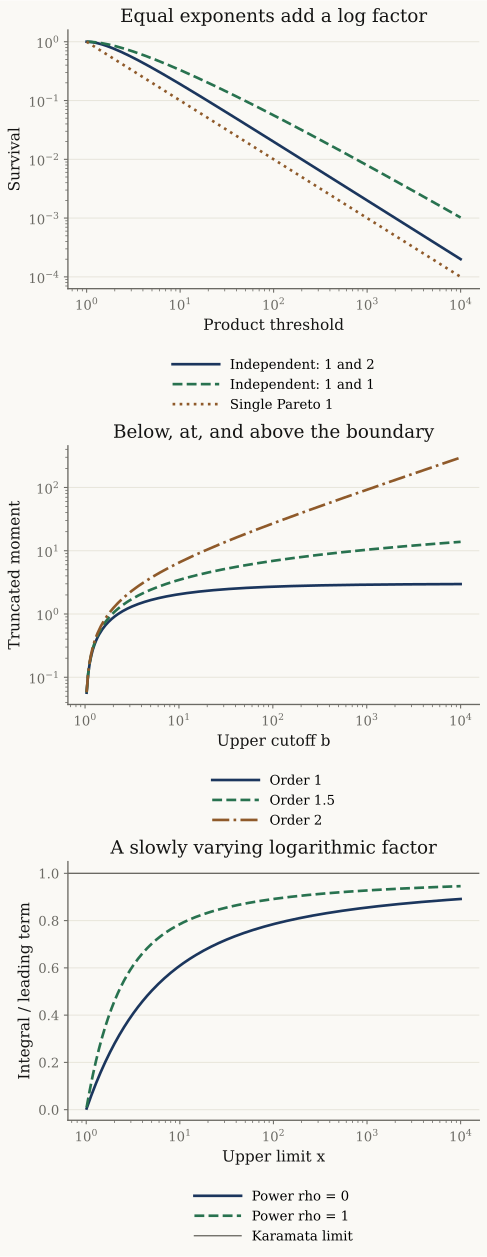
Top: exact independent Pareto products with exponents and , compared with one Pareto of exponent 1; all minima are one. Middle: the three exact truncated moments in the table above, with , on log-log axes. The zero value at is omitted from this panel; the positive curves have no linear-to-log scale transition. Bottom: divided by its Karamata leading term, for . These deterministic calculations illustrate a slowly varying correction and the strict moment boundary; no observations were sampled.
from xmath.incerto.power_laws import pareto_truncated_moment

for order in (1, 1.5, 2):
    moments = pareto_truncated_moment([10, 100, 10000], alpha=1.5, order=order)
    print(f"order={order:.4g}: [" + ", ".join(f"{v:.4g}" for v in moments) + "]")
Output
order=1: [2.051, 2.7, 2.97]
order=1.5: [3.454, 6.908, 13.82]
order=2: [6.487, 27, 297]
These are indicator-truncated population moments; no sample is censored.
Figure regeneration: uv run python demos/incerto/power_laws.py. Each panel uses 241
cutoffs from 1 to 104 (the middle omits the zero endpoint, leaving
240 points; the last begins at 1.01 to avoid a zero leading term). The Pareto product proof
and Karamata calculation
own the other two formulas. The cutoff is the indicator truncation in
, not conditioning on and not the capped moment
.
The chapter’s transformation discussion (§5.2.3, p. 100) and squared Student example (§5.6, pp. 103–105) use different moment orders Taleb, 2025. The moment-estimation note already explains why an existing second moment need not give a finite variance to the empirical average of squares.
Examples¶
If , the mean is infinite because .
If , the mean exists, but the variance is infinite because .
If , the mean and variance exist, while the third raw moment is at the logarithmic boundary and diverges.
The theorem is exact, but sample estimates can still look misleading. With close to a boundary, a finite run can appear calm until a new large observation changes the empirical moment.
For and , the population mean is 6 while the second raw moment is infinite. Any finite sample of finite observations still has a finite sample second moment. Its finiteness does not settle the population question.
Caveats¶
Moment existence is a property of the generating distribution, not proof that a finite sample estimate will be accurate.
When is close to a boundary, convergence can be so slow that the formal moment is a poor operational summary.
For two-sided heavy-tailed variables, check absolute moments or one-sided tails explicitly. Symmetry can make a location parameter look finite while absolute exposure is infinite.
Empirical Pareto fits require threshold checks. A moment calculation using a fitted inherits the uncertainty and bias of the tail fit.
References¶
Taleb (2025), §§5.2.3 and 5.6, pp. 100 and 103–105: power transformations and squared observations; the exact Pareto integral and its equality boundary are proved here.
Bingham et al. (1987), Regular Variation.
Resnick, Heavy-Tail Phenomena 2007.
Backlinks¶
Depends on: Pareto Distribution and Karamata’s Theorem.
Used by: LLN Failure Under Infinite Mean, Pre-Asymptotic LLN Behavior, and Max-to-Sum Ratio.
- Taleb, N. N. (2025). Statistical Consequences of Fat Tails (3rd ed.). https://arxiv.org/abs/2001.10488v4
- Bingham, N. H., Goldie, C. M., & Teugels, J. L. (1987). Regular Variation. Cambridge University Press. 10.1017/CBO9780511721434
- Resnick, S. I. (2007). Heavy-Tail Phenomena: Probabilistic and Statistical Modeling. Springer. 10.1007/978-0-387-45024-7