Overview
How heavy is the upper tail, and how sensitive is the answer to where we start fitting it? Hill estimates the exponent of a positive Pareto-type tail from the largest observations. Choosing how many observations to retain is part of the estimate.
Read the Pareto and regular variation pages first. The formula uses logarithms and sorted observations; the extreme-value index is the reciprocal of the Pareto exponent . For data analysis, inspect several thresholds and check dependence and measurement limits before interpreting a stable-looking curve. Tail threshold selection develops these checks.
Estimator
Let be observed right-tail data with for every , and write the ascending realized order statistics as
For , the Hill estimate of the extreme-value index is
For a Pareto-type right tail with exponent , the corresponding tail exponent estimate is
The tuning parameter is the number of upper order statistics used. A Hill stability plot graphs or over a range of values. On this page, we name the plotted coordinate explicitly: is the extreme-value index, while is the Pareto tail exponent.
Here is the th ascending observation, and selects the top values above the order-statistic threshold. If all selected values equal that threshold, and there is no finite reciprocal estimate. Ties can also make the strict exceedance count smaller than .
When to use it
Hill is a right-tail estimator for strictly positive observations in a Pareto-type regime, meaning the survival tail is expected to be regularly varying. It is appropriate only after deciding what data transformation makes the tail positive and one-sided.
Small means the threshold is very high, so the estimate uses only the most extreme observations and has high variance. Large lowers the threshold, which adds data but can mix non-tail observations into the calculation. A stable region is a practical compromise between those two failures.
Report a range of values, the corresponding thresholds, and the sensitivity of the estimated exponent. A plateau can guide further checks, but it does not establish regular variation or independence.
Exact Pareto calibration
For a Pareto Type I variable,
Define . For ,
so is exponential with mean . Equivalently,
for any Pareto threshold . The Hill estimator replaces this conditional expectation by the empirical average of log-excesses above the random threshold , or by after the sample is realized.
For exact Pareto samples this explains why targets . For a positive iid sample whose right tail is regularly varying with extreme-value index , the standard consistency result uses an intermediate sequence with
Under these assumptions, converges in probability to . The proof of that full theorem belongs to extreme-value asymptotics; we use the exact Pareto calibration and cite the general result in Resnick 2007. Hill’s original estimator is described in his 1975 paper, pp. 1163–1174.
Stability diagnostics
A stability diagnostic repeats the same calculation over and reports both the threshold and the chosen tail coordinate. The arithmetic is visible even in a fixed four-observation example.
Take the fixed ordered observations . The Hill calculation gives:
| Threshold | |||
|---|---|---|---|
| 1 | 4 | ||
| 2 | 2 | ||
| 3 | 1 |
This small deterministic example shows how the selected threshold changes the estimate. It is an illustration of the arithmetic, with no claim that the four values are a random Pareto sample.
In a distribution with a bounded body and a Pareto tail, increasing far enough pulls body observations into the calculation. For empirical data, a plateau is evidence to inspect, not a certificate.
Seeded stability comparison
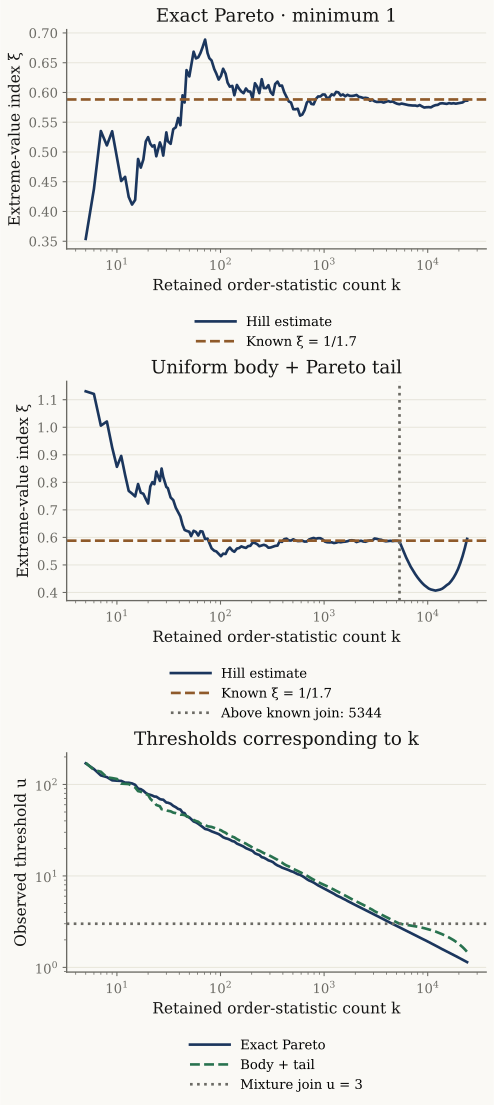
Two iid samples of observations: exact Pareto with , (PCG64 seed 20261020), and the uniform-body/Pareto-tail model (seed 20261021). The mixture is uniform on with probability 0.82 and Pareto with minimum 3, exponent 1.7, otherwise. Both tail targets are . The marked count of 5,344 is realized, not its population expectation. The third panel maps to ; these continuous draws have no ties, so strict exceedance counts equal . Increasing eventually includes the mixture body. A stable-looking segment supplies no unique threshold choice.
Use pareto_type1 and
hill_stability to reproduce
selected points of the first panel:
import numpy as np
from xmath.incerto.distributions import pareto_type1
from xmath.incerto.estimators import hill_stability

x = pareto_type1.rvs(1.7, size=30000, random_state=np.random.default_rng(20261020))
hill = hill_stability(x, [50, 500, 5000])
for k, xi in zip(hill["k"], hill["xi"]):
    print(f"k={int(k):d}: xi={xi:.4g}, truth={1/1.7:.4g}")
Output
k=50: xi=0.627, truth=0.5882
k=500: xi=0.5728, truth=0.5882
k=5000: xi=0.58, truth=0.5882
Regenerate all panels with uv run python demos/incerto/tail_estimation.py.
The same mixture sample supplies the coordinated threshold diagnostics.
Failure modes
Hill is a right-tail estimator for strictly positive data: every realized input must satisfy . Transform or split two-sided data before using it.
The estimator is threshold-sensitive. A reported should include the selected , the threshold, and a stability plot.
A plateau is suggestive, not a proof of a Pareto tail. Dependence, mixtures, truncation, and measurement limits can all manufacture or destroy apparent stability.
Estimating and plugging it into moments is dangerous near moment boundaries. Small estimation error around or can change whether a mean or variance is treated as finite.
The reciprocal is unstable when is close to zero. Thin-tail regimes need different tools.
References
Hill, “A Simple General Approach to Inference About the Tail of a Distribution” 1975.
Embrechts, Klueppelberg, and Mikosch, Modelling Extremal Events 1997.
Resnick, Heavy-Tail Phenomena 2007.
Backlinks
Depends on: Pareto Distribution, Regular Variation, and the shared tail notation in Shared notation.
Used by: Extreme Value Index Estimation, Tail Threshold Selection, and S&P 500 Tail Diagnostics.
- Resnick, S. I. (2007). Heavy-Tail Phenomena: Probabilistic and Statistical Modeling. Springer. 10.1007/978-0-387-45024-7
- Hill, B. M. (1975). A Simple General Approach to Inference About the Tail of a Distribution. The Annals of Statistics, 3(5), 1163–1174. 10.1214/aos/1176343247
- Embrechts, P., Klüppelberg, C., & Mikosch, T. (1997). Modelling Extremal Events. Springer. 10.1007/978-3-642-33483-2