Statement¶
For a right-tail survival function , the survival tail-ratio diagnostic is
where . With iid copies and , the numerator is
Thus compares a two-coordinate moderate-extreme event with a one-coordinate double-threshold event. It is a tail-geometry diagnostic, not an estimator by itself.
Here is the comparison threshold, is the CDF, and , are the Pareto exponent and lower cutoff. is distinct from the regular-variation ratio .
Calibration cases¶
The diagnostic separates three useful geometries:
| Tail model | behavior | Reading |
|---|---|---|
| Pareto, | A single doubled observation is eventually more likely than two independent observations above . | |
| Exponential, | 1 | Two -exceedances and one -exceedance have the same exponential cost. |
| Standard normal | Two moderate extremes are much more likely than one doubled extreme. |
The Pareto calculation is exact once . The normal calculation uses Mills’ ratio, , for the standard Gaussian tail. This also follows from the complementary-error function expansion in NIST DLMF, Section 7.12.
The regular variation connection is simple. If with , then
Therefore
So regularly varying tails fall on the one-big-jump side of this diagnostic. That agrees with subexponentiality, though is only a diagnostic ratio and not the full convolution-tail definition.
Static calibration¶
For an exact Pareto law with and , for . The exponential comparison is exactly one at every positive threshold.
| Threshold | Pareto | Exponential |
|---|---|---|
| 2 | 1 | 1 |
| 4 | 1 | |
| 8 | 1 | |
| 16 | 1 |
A heavy-tailed model can therefore have at finite thresholds; the asymptotic direction and the range inspected both matter. For the normal, substitution of Mills’ ratio gives
Student-t tails with positive degrees of freedom (including the Cauchy case) are regularly varying, so the preceding regular-variation argument gives . These are population calculations, not empirical fits.
What a borderline ratio does and does not establish¶
SCoFT v4 §§5.0.2–5.0.3, pp. 93–95 Taleb, 2025, motivates this event comparison with exponential and sigmoid survivals. We derive their values here and keep them separate from a convolution-tail criterion.
For centered logistic survival , ,
This law is light-tailed. Its density is bounded by a constant times
, so its MGF is finite for by comparison
with an exponential integral on each half-line. The density is
, the hypsecant2 helper’s law
with loc=0, scale=1/k.
The name identifies this squared-secant convention, not the ordinary
hyperbolic-secant distribution.
For a centered Laplace law with scale , the right survival is on , giving . More generally, implies . Translating by changes that constant to . Thus the value one is not an invariant boundary between light and heavy tails. It reflects the tail prefactor as well as its decay.
For Weibull survival on ,
It tends to , zero, or as , , or . The catalog supplies the separate subexponential classification for the first range. A vanishing is not a proof of the full convolution condition.
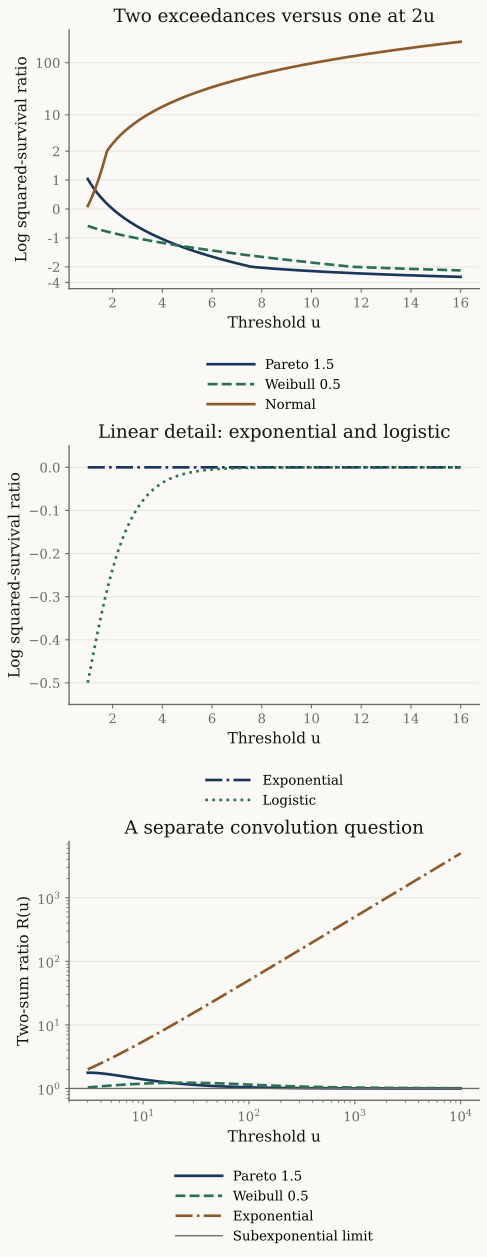
Top and middle: exact at 241 thresholds between 1 and 16 for Pareto , Weibull shape , rate-one exponential, centered logistic with , and standard normal. The top uses a symmetric-log axis with explicit negative and positive ticks. The middle separates the two curves near zero on a linear axis: exponential is exactly zero, while logistic approaches zero from below. Bottom: numerical convolution ratios at 81 thresholds from 3 to 104 for Pareto , Weibull shape , and rate-one exponential. The finite plots illustrate different questions; only the convolution ratio defines subexponentiality.
Use pareto_type1, iid_two_sum_tail.
import numpy as np
from xmath.incerto.distributions import pareto_type1
from xmath.incerto.tail_diagnostics import iid_two_sum_tail

law = pareto_type1(1.5)
u = np.array([3., 10., 100.])
ratio = np.exp(2 * law.logsf(u) - law.logsf(2 * u))
print("Squared-survival ratio: [" + ", ".join(f"{v:.4g}" for v in ratio) + "]")
result = iid_two_sum_tail(law, u)
assert result["success"].all()
print("Two-sum ratio: [" + ", ".join(f"{v:.4g}" for v in result["ratio"]) + "]")
Output
Squared-survival ratio: [0.5443, 0.08944, 0.002828]
Two-sum ratio: [1.769, 1.391, 1.044]
The convolution ratio uses independent summands.
Figure regeneration: uv run python demos/incerto/power_laws.py. Log survival values prevent
division of underflowed probabilities. The convolution helper uses
one-dimensional adaptive quadrature; the demo stops on a failed error check.
No random sampling or empirical fitting is involved.
Caveats¶
is a distribution-level diagnostic. A finite empirical estimate can be dominated by sampling noise because both the numerator and denominator involve rare events.
The iid interpretation of fails under dependence. Clustered extremes need their own dependence model before this ratio can be read as a joint-event probability.
The ratio uses right tails. Two-sided returns, losses, and absolute values require an explicit transformation before the diagnostic is applied.
is compatible with one-big-jump geometry, but it is not a replacement for the convolution-tail definition of Subexponentiality.
References¶
Taleb (2025), §§5.0.2–5.0.3, pp. 93–95: event-ratio context. The limiting prefactor and translation calculations are proved here.
Feller, An Introduction to Probability Theory and Its Applications, Vol. II (2nd ed., Wiley, 1971).
Embrechts, Klueppelberg, and Mikosch, Modelling Extremal Events 1997.
Backlinks¶
Depends on: Regular Variation and Subexponentiality.
Related catalog: Tail Class Catalog.
Related diagnostic: Max-to-Sum Ratio.
Used by: Iso-Density Tail Geometry.
- Taleb, N. N. (2025). Statistical Consequences of Fat Tails (3rd ed.). https://arxiv.org/abs/2001.10488v4
- Embrechts, P., Klüppelberg, C., & Mikosch, T. (1997). Modelling Extremal Events. Springer. 10.1007/978-3-642-33483-2