Statement
The generalized Pareto distribution is the standard limit family for threshold excesses. With location zero, an excess variable has shape and scale when
for with . For the CDF is zero; for it is one at and above , by continuity. The boundary case is
For , the support is . For , the support is , so the tail has a finite endpoint. The survival function for is
The mean exists only for and equals . The variance exists only for and equals
Shape and endpoint intuition
The generalized Pareto distribution is the peaks-over-threshold counterpart of the generalized extreme-value distribution for block maxima. Once a threshold is high enough, the distribution of the excess over that threshold is modeled with one shape parameter and one scale parameter .
The sign and size of carry the tail story. Positive gives a Pareto-type heavy tail. Zero gives the exponential boundary. Negative gives a finite endpoint. In the fat-tail examples, the most important boundary values are for variance and for the mean.
For , the three examples from the survival formula are:
| Shape | Survival | Upper endpoint |
|---|---|---|
| -0.4 | for | 2.5 |
| 0 | for | Infinite |
| 0.4 | for | Infinite |
What to notice. Positive gives the slowest-decaying curve, is the exponential boundary, and negative ends at the finite endpoint .
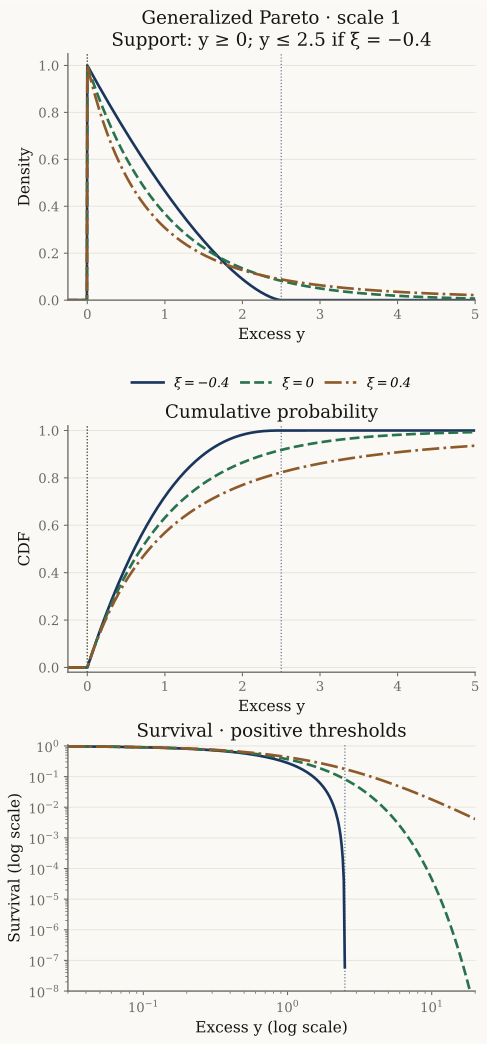
Figure 1:Exact GPD laws with and . All start at zero; the negative-shape law ends at , marked by a matching dotted line. Its CDF stays at one beyond that point. Zero survival is omitted on logarithmic axes; it is never replaced by a small positive probability. The survival viewport starts at 10-8.
Use generalized_pareto.
The endpoint calculation is visible in the returned CDF and survival:
from xmath.incerto.distributions import generalized_pareto

law = generalized_pareto(-0.4, beta=1)
for y in (0, 1, 2.5, 3):
    print(f"y={y:.4g}: pdf={law.pdf(y):.4g}, cdf={law.cdf(y):.4g}, sf={law.sf(y):.4g}")
Output
y=0: pdf=1, cdf=0, sf=1
y=1: pdf=0.4648, cdf=0.7211, sf=0.2789
y=2.5: pdf=0, cdf=1, sf=0
y=3: pdf=0, cdf=1, sf=0
Regenerate the card with uv run python demos/incerto/distribution_cards.py.
Threshold-excess stability and Pareto special case
A GPD is stable under raising the threshold. If has parameters and satisfies , then, for admissible and ,
For , the ratio is . Thus excesses have the same shape and updated scale . Combining this with the GPD mean gives the mean-excess formula.
The Pareto Type I distribution is an exact generalized Pareto excess model. If has Pareto tail exponent and threshold , then
This is the generalized Pareto survival function with
The Pickands-Balkema-de Haan theorem explains why the same family appears asymptotically for a much larger class of threshold exceedances.
Formula check
A concrete choice of shape and scale illustrates both the survival and moments.
For and , direct substitution gives
Thus , , , and . These are formula evaluations, with no numerical fitting or simulation.
Caveats
A GPD fit is a tail model for exceedances, not a model for the full distribution body.
The threshold is not chosen by the theorem. Shape and scale estimates should be inspected across a range of thresholds.
When , the fitted excess distribution has no finite mean. When , it has no finite variance.
Dependence, truncation, censoring, seasonality, and mixture effects can distort threshold-excess fits.
References
Balkema and de Haan, “Residual Life Time at Great Age” 1974.
Pickands, “Statistical Inference Using Extreme Order Statistics” 1975.
Davison and Smith, “Models for Exceedances over High Thresholds” 1990.
Coles, An Introduction to Statistical Modeling of Extreme Values 2001.
Embrechts, Klueppelberg, and Mikosch, Modelling Extremal Events 1997.
Backlinks
Depends on: Extreme-Value Index Estimation and the shared tail notation in Shared notation.
Used by: Pickands-Balkema-de Haan Theorem, Mean Excess Function, and Tail Threshold Selection.
- Balkema, A. A., & de Haan, L. (1974). Residual Life Time at Great Age. The Annals of Probability, 2(5), 792–804. 10.1214/aop/1176996548
- Pickands, J. (1975). Statistical Inference Using Extreme Order Statistics. The Annals of Statistics, 3(1), 119–131. 10.1214/aos/1176343003
- Davison, A. C., & Smith, R. L. (1990). Models for Exceedances over High Thresholds. Journal of the Royal Statistical Society: Series B (Methodological), 52(3), 393–442. 10.1111/j.2517-6161.1990.tb01796.x
- Coles, S. (2001). An Introduction to Statistical Modeling of Extreme Values. Springer. 10.1007/978-1-4471-3675-0
- Embrechts, P., Klüppelberg, C., & Mikosch, T. (1997). Modelling Extremal Events. Springer. 10.1007/978-3-642-33483-2