Statement
The generalized extreme-value distribution is the standard limit family for normalized block maxima. With location , scale , shape , and standardized variable , its CDF is
where . For , extend the CDF by zero at and below ; for , extend it by one at and above . The boundary case is the Gumbel law,
The shape parameter is the same extreme-value index used in threshold excesses: is Frechet-type heavy-tail behavior, is Gumbel-type behavior, and is Weibull-type finite endpoint. Here are observations and . The Pareto example below uses lower cutoff and exponent . Gumbel attraction is broader than exponential parent tails: normal and lognormal parents are examples, despite their different tail decay.
Maxima intuition
The distribution is to block maxima what the Generalized Pareto Distribution is to threshold exceedances. For iid observations, if there are constants and such that converges to a nondegenerate law, that law is a GEV distribution up to location and scale. Existence of such a limit is an assumption; it does not hold for every parent law.
For fat-tail work, is the main case. A Pareto tail with exponent has , so the fitted block-maximum shape should point to the same tail coordinate as a Hill or GPD threshold analysis when the modeling assumptions are reasonable.
Shape regimes
With and , the support makes the three shapes explicit.
| Shape | Interior CDF | Support |
|---|---|---|
| -0.3 | ; CDF is one above | |
| 0 | All real | |
| 0.3 | ; CDF is zero below |
Every curve passes through . Positive shape gives a power-law right tail; negative shape gives a finite right endpoint.
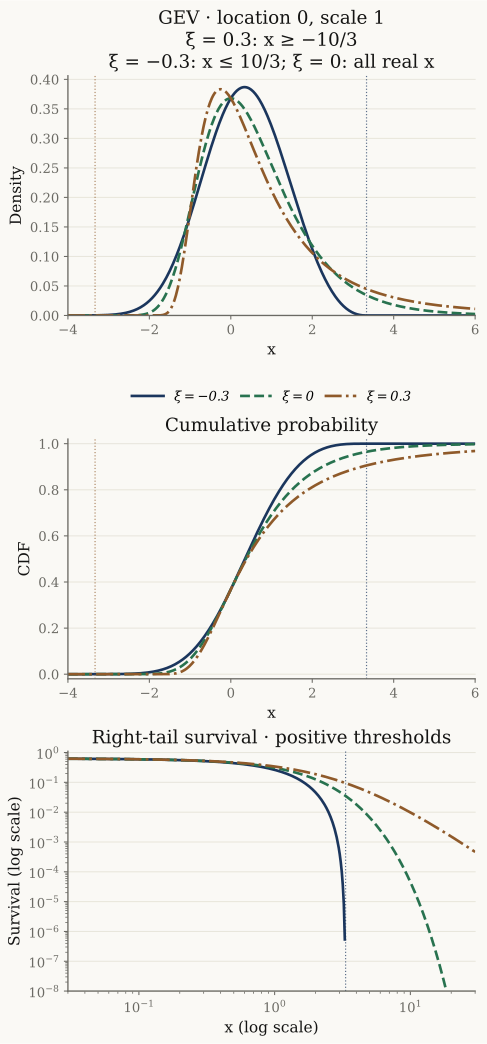
Figure 1:Exact GEV laws with and . The dotted boundaries are for positive shape and for negative shape. The Gumbel law has no finite endpoint. The log-log panel shows only positive thresholds, with survival below 10-8 outside the viewport and exact zero omitted.
generalized_extreme_value
uses the shape sign in this page’s CDF. It passes c=-xi to
SciPy’s genextreme.
from xmath.incerto.distributions import generalized_extreme_value

for xi in (-0.3, 0, 0.3):
    law = generalized_extreme_value(xi)
    left, right = law.support()
    print(f"xi={xi:.4g}: support=[{left:.4g}, {right:.4g}], cdf(0)={law.cdf(0):.4g}")
Output
xi=-0.3: support=[-inf, 3.333], cdf(0)=0.3679
xi=0: support=[-inf, inf], cdf(0)=0.3679
xi=0.3: support=[-3.333, inf], cdf(0)=0.3679
Regenerate the card with uv run python demos/incerto/distribution_cards.py.
Pareto block maxima example
If are iid Pareto Type I with lower cutoff and exponent , then for ,
With , for fixed and sufficiently large ,
This is the Frechet member of the GEV family with after a standard location-scale reparameterization.
Block-size calibration
For an exact Pareto parent with , the limiting shape is . At block size , the normalizing scale is . At the normalized threshold ,
This compares an exact finite-block CDF with its limit; it is not a GEV fit or an assessment of sampling uncertainty. The standard Frechet limit has GEV parameters on the normalized scale.
Caveats
Block maxima discard within-block information. Threshold methods may use extremes more efficiently, but they require a threshold choice.
Blocks should be chosen with dependence and seasonality in mind. Overlapping or strongly dependent blocks can make fitted uncertainty too optimistic.
A GEV fit describes maxima, not the entire parent distribution.
Software may use a different shape sign convention. Translate fitted parameters into the displayed CDF before comparing maxima and excesses.
References
Embrechts, Klueppelberg, and Mikosch, Modelling Extremal Events 1997.
Resnick, Heavy-Tail Phenomena 2007.
Coles, An Introduction to Statistical Modeling of Extreme Values 2001.
Feller, An Introduction to Probability Theory and Its Applications, Vol. II (2nd ed., Wiley, 1971).
Backlinks
Depends on: Extreme-Value Index Estimation.
Used by: Frechet Distribution and Frechet-Type Limits, Pickands-Balkema-de Haan Theorem as the block-maxima counterpart to threshold excess limits, and by future return-level pages.
- Embrechts, P., Klüppelberg, C., & Mikosch, T. (1997). Modelling Extremal Events. Springer. 10.1007/978-3-642-33483-2
- Resnick, S. I. (2007). Heavy-Tail Phenomena: Probabilistic and Statistical Modeling. Springer. 10.1007/978-0-387-45024-7
- Coles, S. (2001). An Introduction to Statistical Modeling of Extreme Values. Springer. 10.1007/978-1-4471-3675-0